Articles published in Akiya Lab | Roopt (Makigumi)
Makigumi, which operates Roopt, constantly researches case studies and other information on the revitalization of vacant houses and publishes them as columns.
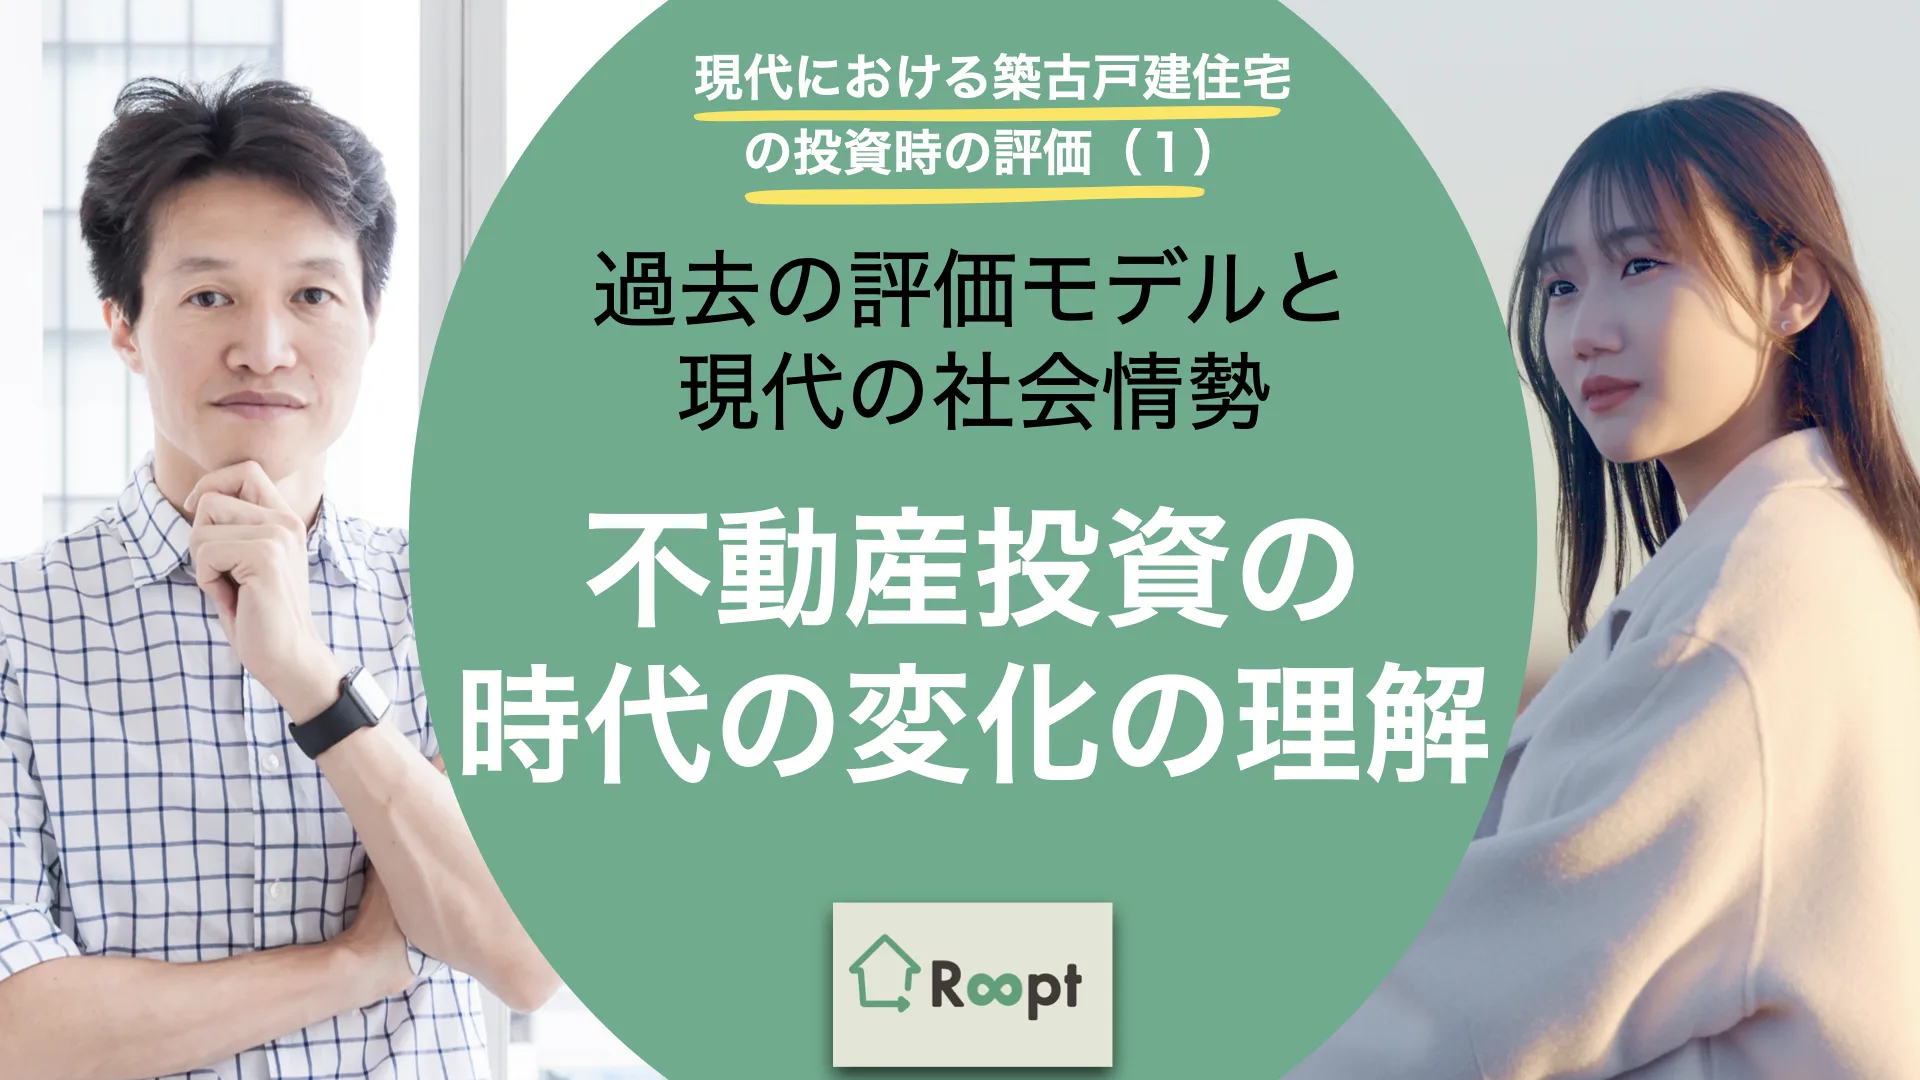
This video, the first in the series, provides an overview of how old detached properties have been evaluated in the past and what perspectives will be needed in the future.
Noi: Hello everyone, I'm Noi, assisting with Gaiax and Makigumi's projects. In this video, we'll be discussing the evaluation of old detached houses at the time of investment in the modern era with Mr. Ueda, President and CEO of Gaiax. Currently, vacant houses and old properties are not highly valued by financial institutions, but it is expected that the number of vacant and old properties will continue to increase in the future. What measures can be taken to ensure that such properties receive evaluation from financial institutions? This time, Mr. Ueda, CEO of Gaiax, who invests in properties that cannot be rebuilt, will discuss evaluation models based on current social conditions. Mr. Ueda, thank you for joining us.
Ueda: Thank you. Gaiax itself does some real estate investment, and as Noi just mentioned, we invest in companies that invest in old properties, and I also personally look at various real estate investments. So, based on those experiences, I'd like to share my opinions as an investor, and I hope financial institutions will consider these points.
Noi: So, let's start with the scope of this discussion.
Ueda: Basically, I won't be dealing with commercial buildings or anything like that. I'll be focusing on properties that are typically around 20 to 30 million yen at most, and in some cases, even "negative assets" – not in the sense of losing money, but rather properties where you pay someone 5 to 10 million yen to dispose of them. Most of these properties will be in the 5 to 10 million yen range, old, detached, wooden structures, and primarily in rural areas rather than central Tokyo. And importantly, I'll be focusing on cases involving properties with unfavorable conditions, such as those that cannot be rebuilt. I'd like to discuss such cases in particular.
Noi: Regarding the outline of the ideal situation, how do you think we should approach this, Mr. Ueda? Please tell us more.
Ueda: I'm planning to talk about this over several videos, but I'd like to give an overview first. Until now, real estate has truly been viewed as real estate, with questions like, "What is the value of this property?" or "What is the value of this property, so how much can we lend?" However, Makigumi, Gaiax, and other companies that Gaiax invests in, don't simply view real estate as real estate. They view it as a fundamental asset for conducting business. Specifically, we operate share houses and vacation rentals.
When we evaluate real estate, how do we do it? We look at the basic value, which is somewhat similar to how it was done before, but we also consider how much value it can generate if used for a business. We look at both and make a comprehensive evaluation. Specifically, we adopt the higher value.
When we look at the market price, if the market price is higher, there's no need for us to get involved, so that's not really the topic of today's discussion. However, when we see a property as a treasure from a business perspective, we adopt that value.
I'd like to briefly explain these two aspects: the basic value, which is commonly used, and the business value assessment. The basic value is essentially the same as previous approaches, so there's not much to comment on. However, even with basic value, existing approaches tend to underestimate rentals. To put it another way, they are too influenced by the idea of building new, or buying land to build new. We should consider that properties can be used for rentals much more now. In other words, if renting is acceptable, there's no need for new construction; old properties are fine, and the buying and selling of old properties should be evaluated more highly, I believe.
In addition, while the evaluation of individual plots of land is important, for companies or individuals undertaking a business, it's not just about individual plots of land. The overall evaluation of the entire business is also a problem. Real estate evaluation is quite difficult, or rather, it's only evaluated as real estate, which is problematic. So, when viewed as a business, for example, if someone owns 10 properties and operates share houses or vacation rentals in them, or even just rentals, we should consider more deeply what the overall balance sheet and profit and loss statement of that company look like.
Noi: Thank you. To evaluate an old detached house, it's not enough to just look at the building itself. You also need to consider what kind of business is being conducted or could be conducted there. And as you mentioned earlier, the flow of money can change depending on who rents it, which creates another difficult problem. So, it's a very complex issue that requires looking at various aspects such as business, local community, and who is operating it, rather than being able to say definitively how it should be evaluated.
Ueda: First, I'd like to organize how properties have been evaluated in the world until now. Noi, how do you think about evaluating real estate, or more specifically, getting a loan for real estate, which is common? In your daily life, where have you encountered discussions about financial institutions lending or not lending money for housing or real estate, or how the amount is determined? What kind of image do you have?
: I had a little exposure to it when my parents took out a loan when my family home was built. I have the impression that it's difficult to get a loan unless there's a definite guarantee of repayment, and that they are strict about how the money will be used and whether the property meets the conditions for construction.Noi
: I had a little exposure to it when my parents took out a loan when my family home was built. I have the impression that it's difficult to get a loan unless there's a definite guarantee of repayment, and that they are strict about how the money will be used and whether the property meets the conditions for construction.: How old were you then, by the way?
Noi: I was going into high school.
Ueda: How many people are in your family? Three or four?
Noi: Three.
Ueda: Three people. That's a very common scene in the world, a family of three taking out a housing loan, discussing how many years the loan repayment should be, and wondering if the father's age alone is enough to repay it.
Noi: That's right. My father, whether he's joking or serious, always tells me it's a two-generation loan, so I have to earn money.
Ueda: Right. I'm sure none of you feel any discomfort with this, but I think this is how the world generally works. What do you think financial institutions actually believe in when they lend money?
Noi: Whether you can repay it is the most important thing they look at, isn't it?
Ueda: That's right. Behind the question of whether you can repay it, and this varies from case to case, is the assumption of where your father works and whether he will continue to work indefinitely. This is where it gets strange.
Certainly, in old Japan, such families were common, and long-term loans were arranged for such families to build new houses. It's true that things are completely different now, but perhaps financial institutions are still operating in the same way? In fact, they often are.
In other words, they are not lending money based on the creditworthiness of the land or building, but rather based on the creditworthiness of the working father. And the premise is that they won't move. Of course, they assume long-term use without moving, and of course, it's probably new construction, and this is related: because it's new construction, the land is evaluated as land for new construction, as that's how the world builds new houses.
When there's a 40-year-old building on a piece of land, how is it evaluated? They'll say, "Is this for sale?" Then, "If we clear the land and build new, the existing building has zero value. Okay, it's land. The value of this land is X." This happens too often, where new construction is built, and the land is evaluated based on that.
Next, regarding properties that cannot be rebuilt, there are lands where a building can be rebuilt, and lands where once a building is demolished, no new building can be constructed. This applies to lands not adjacent to a road. If a building were to be rebuilt there, it would be problematic in case of a fire, for example. So, the policy is to merge such land with land that is adjacent to a road and then rebuild. Lands not sufficiently adjacent to a road can become properties that cannot be rebuilt.
How were they evaluated until now? Since everyone was focused on new construction, they didn't evaluate the existing buildings.
This is how it has been: there was a model of Japanese people, and a scheme for financing based on that. One more thing I want to say is that they are not lending based on the land or building, but on the person, so if the person cannot repay, they are the one who has to repay.
In America, when you buy a property, it's common for loans to be secured by the property itself, and not tied to the borrower. For example, if Noi buys land for 20 million yen. She goes to a financial institution. They might say, "Well, it's currently trading at 20 million yen, but real estate land prices fluctuate, and we, as a bank, can't take on that risk, so we'll lend you 15 million yen. Please use this building as collateral for the 15 million yen loan." So, Noi puts in 5 million yen, combines it with the 15 million yen loan, and buys the land for 20 million yen.
For example, after 5 years, if you've repaid 2 to 3 million yen, and Noi tries to sell the building, if the remaining loan is 12 million yen (assuming 3 million has been repaid), if it sells for more than 12 million yen, she repays 12 million yen. But even if it sells for less than 12 million yen, Noi is not held responsible.
In America, even if a person works for a good company, the loan isn't tied to them. So, if you say, "I work for a top-tier company," they might say, "No, no, it's wrong to buy such a worthless piece of land for 20 million yen." They might lend you money, but because it's a worthless piece of land, they'll only lend you 5 million yen.
In the US, the amount you can borrow is determined by the condition of the land or building. So, financial institutions are desperate to evaluate the land and building. How much would it actually resell for? Naturally, it's more efficient overall to keep using usable houses and pass them on to the next generation, rather than demolishing usable houses to build new ones, only to demolish them again to build new ones.
Noi: Thank you. Based on that past discussion, what are the current social conditions for creating future models?
Ueda: Right. This is so obvious that I don't even need to say it, but lifestyles have changed, haven't they? I'll explain this in more detail later, but first, lifestyles have changed. And demographic trends have also changed quite a bit, that's one point.
Second, and this is also quite important, work styles such as workation and remote work have become widespread. This means that the concept of where you work is being liberated from where you live.
: Third, the sharing economy has become widespread in society. Let's share various things. And with what we've shared, we can do various things, right? Specifically, vacation rentals and share houses. And services that combine these, such as ADDress and many others, are examples of the widespread sharing economy.
The fourth change is, without a doubt, technology. In the construction industry, for example, what used to last only 20 years can now last 50 or 100 years. And various technologies, such as those related to finance, are advancing, which is changing the world.
These changes, of course, mean that the lending style tailored to the Japanese lifestyle created 50 years ago has changed in various ways over these 50 years, as I just mentioned. That is the current social situation.
Ueda: Here, I'd like to discuss one more thing based on that. The relationship between financial institutions not recognizing value and therefore not lending money with collateral, and the property not having value when actually sold, is quite complex. Many people think that because it has no value, financial institutions don't set collateral. However, there are many cases where the opposite is true: because financial institutions don't recognize collateral value and don't lend money, the market price is low.
For example, a piece of land owned by Noi, according to past societal thinking, was only worth 1 million yen. However, considering the current social context, it actually has a value of 10 million yen. If I were to go buy that land, I'd say, "Noi, please sell me that land." When Noi says, "Okay," I'd say, "Then I'll consult with a financial institution, look at my available funds and the amount I can borrow, and then make you an offer." When I take it to the financial institution, they might say, "Oh, that land? We can only lend you 1 million yen to buy it." Or, they might say, "Oh, that land? Considering current times, it's worth about 10 million yen, isn't it? We can lend you as much as you need, up to 10 million yen." The amount I offer Noi would change, wouldn't it?
The reality is that even though it could be evaluated higher, people don't have a lot of cash on hand, so they say, "It's still tough," and buy it. This is the same with renovations. There are many cases where an old building could be used more if it were renovated, but if you go to a bank and say, "I want to renovate a 1 million yen property, please lend me money, I'll put the property up as collateral," they won't deal with you.
The reason there are so many vacant houses in the world right now that are in a dead-end situation is because they haven't been evaluated. It's understandable that they can't be evaluated even with new lifestyles. It's a dead-end, so it can't be evaluated, and that's unavoidable. But I think it's a huge waste that they aren't being evaluated when they could be, considering current lifestyles.
The background to this is rooted in what I mentioned earlier: lending money based on a person's attributes. The fact that property evaluations, or loans not tied to individuals (non-recourse loans), are not being made, and that used properties are not moving or being refreshed, are all interconnected problems, I believe.
Finally, I want to tell everyone that there's a general impression in the real estate industry that building new properties, taking out 30-year loans, and lending at low interest rates to high-attribute individuals working for top-tier companies is a "clean" area. On the other hand, real estate investors who buy cheap and sell high, or buy cheap and renovate to make properties usable, or who present various proposals for properties that financial institutions are reluctant to deal with, and use various schemes to pull money from financial institutions and leverage it to make a profit, are seen as being in a "not so clean" area. But I want to say that this is absolutely not true.
To use another analogy, I think many people feel the same way about the car industry. Buying a new car seems like a "clean" industry. But the used car industry seems to have a somewhat complicated smell, people might say. However, if everyone scrapped their used cars and bought new ones, would that be good for society? No, it wouldn't. It's definitely better to keep using used cars as much as possible.
The point is, problems exist everywhere. It's crucial to make things cleaner, more transparent, and utilize resources as effectively as possible. In fact, how to develop the used industry is more important for society than new construction. I want everyone to feel this point for future social impact.
Noi: Mr. Ueda, thank you for your talk. This time, we discussed the evaluation of old detached houses at the time of investment in the modern era, based on past evaluation models and current social conditions. Next time, we plan to upload videos that delve deeper into the topics Mr. Ueda mentioned earlier, such as lifestyles, demographics, workation, remote work, and the sharing economy. Please watch the next episode as well. Thank you.
Ueda: Thank you.
First published: Akiya Lab (2024 - now integrated into this site)
FIND YOUR STAY
Feel free to contact us for inquiries about accommodation reservations, move-in consultations, viewing appointments, interviews, etc.
Contact Us